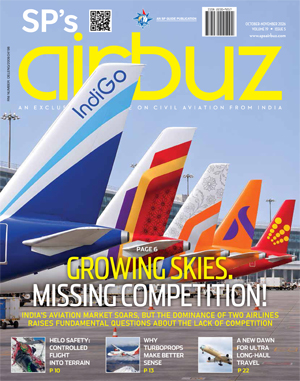

IndiGo’s rise is one of Indian aviation’s great success stories. But as one carrier approaches two-thirds of the domestic market and two airline groups together account for roughly nine out of every ten passengers, India faces a larger question: can one of the world’s fastestgrowing aviation markets thrive without more meaningful competition?
There has perhaps never been a more exciting time for Indian civil aviation. New airports are opening and Indian carriers have placed some of the largest aircraft orders in aviation history. Yet while the market expands rapidly, meaningful competition within it has been shrinking.
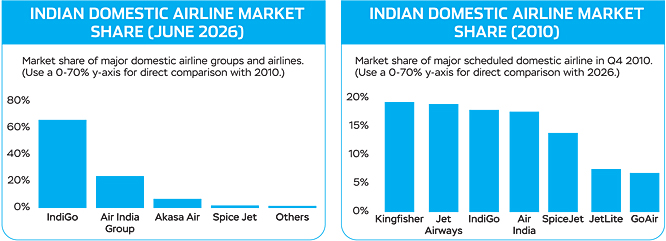
In June 2026, IndiGo carried 89.2 lakh domestic passengers and held 66.3 per cent of the domestic market. The Air India Group had 23.9 per cent, Akasa Air 6.4 per cent and SpiceJet 1.9 per cent. Put another way, roughly nine out of every ten domestic passengers in India now fly with one of two airline groups.
That deserves attention — but not because IndiGo has done something wrong. Its rise rests on nearly two decades of disciplined expansion and cost control in an industry notorious for destroying capital. The problem is not that IndiGo became successful. It is that too few airlines have remained successful alongside it.
A VERY DIFFERENT AVIATION MARKET
In the fourth quarter of 2010, Kingfisher Airlines held 18.9 per cent of domestic traffic, Jet Airways 18.6 per cent, IndiGo 17.6 per cent, Air India 17.3 per cent, SpiceJet 13.6 per cent, JetLite 7.4 per cent and GoAir 6.7 per cent. No airline controlled even a fifth of the market, and several could make independent decisions that influenced their rivals.
Then the landscape changed. Kingfisher stopped flying in 2012, Jet Airways in 2019 and Go First in 2023. SpiceJet survived, much smaller. AIX Connect merged into Air India Express in October 2024, and Vistara into Air India the following month. Meanwhile, IndiGo kept growing. No regulator designed this; it was the result of failures, consolidation and one carrier executing consistently. India has travelled from a market where several airlines held shares in the teens to one where a single carrier holds close to two-thirds.
That does not make IndiGo a monopoly. Rivals still operate, and a market can be concentrated nationally yet fiercely competitive on particular city pairs; a traveller buys Delhi-Mumbai, not “Indian aviation”. IndiGo’s Rahul Bhatia notes that roughly a third of its capacity serves routes with no comparable rival — a fair defence of its scale.
Yet the same argument reveals the vulnerability. If large parts of India’s aviation network depend disproportionately on one carrier, a disruption at that airline can quickly become a disruption to the wider transport system. The issue is less monopoly in the legal sense than concentration risk. Every airline suffers disruption; in a fragmented market rivals absorb some of it, but in a concentrated one the system has less redundancy.
Airline competition is often discussed only in terms of ticket prices, but its influence is wider. Several serious airlines on a route compete over timings, frequency, loyalty programmes, corporate contracts and service. This pressure often works long before a regulator gets involved: a dominant airline need not abuse its position for concentration to matter, because credible alternatives change commercial behaviour. India needs several airlines with sufficient scale to influence one another.
THE AIR INDIA PARADOX — AND WHAT AMERICA LEARNED
The privatisation of Air India was necessary, giving it private capital and a long-term strategy. Consolidating Tata’s four airlines into two — full-service Air India and low-cost Air India Express — also made business sense, removing duplication and building scale.
Yet from a competition perspective, two independent decision-makers disappeared. Their aircraft remained; their ability to compete independently did not. The paradox is that India may gain a much stronger challenger to IndiGo — something the market clearly needs — while having fewer independent competitors.
The transformation also remains unfinished, and Tata Sons acknowledges the turnaround could take years. India therefore has the foundations of a formidable second airline group. What it does not yet have is an equally formidable third or fourth.
For consumers, the effects of concentration are hard to see: flights keep increasing and fares can remain attractive. But the consequences emerge gradually. Fewer substantial competitors mean fewer alternatives when disruption occurs, less aggressive capacity competition on some routes and weaker pressure to improve products. And once a market becomes prohibitively difficult for newcomers to enter, restoring competition is much harder.
The American industry is hardly an ideal model, yet US regulators have shown there are limits to consolidation. When American Airlines and US Airways merged in 2013, the Department of Justice challenged the deal; it proceeded only after the airlines surrendered slots and facilities at airports including Washington Reagan and New York LaGuardia, so rivals could challenge the enlarged airline.
A decade later, a federal court blocked JetBlue’s $3.8 billion acquisition of Spirit Airlines in January 2024, after the Justice Department sued. Spirit’s ultra-low-cost model pressured the fares of larger airlines, so its importance exceeded its market share. Remove an independent competitor and you remove the pressure it places on everyone else.
That is highly relevant to India. The value of Vistara, Go First or Jet Airways cannot be measured only by the passengers they carried. Competition is most valuable because of decisions that never happen: the fare increase not made, the frequency not cut.
SO WHERE ARE INDIA’S NEW AIRLINES?
If India needs stronger third and fourth competitors, why are investors not rushing to create them? Starting an airline is difficult almost everywhere. Building one in India adds a particular set of challenges. Major costs are dollar-denominated while revenue is largely in rupees, fuel is volatile and heavily taxed, airport charges bite in a price-sensitive market, and supply-chain problems can ground capacity. Indian aviation has repeatedly shown that enormous passenger demand does not automatically translate into sustainable airline profits.
Scale is the next obstacle. IndiGo and Air India have nationwide networks, corporate contracts and order books measured in hundreds. A start-up entering with ten or twenty aircraft is not merely competing against another airline. It is competing against a network. Akasa Air, operating only since 2022, shows entry is still possible; India needs more stories like it.
A new airline also needs somewhere useful to fly. At India’s busiest airports, attractive slots are increasingly valuable; a 2:30 a.m. departure is no alternative to an 8:00 a.m. flight. Incumbents should not lose capacity for being successful, but if practically every attractive slot remains permanently concentrated among them, a newcomer may struggle to build a competitive network regardless of how well financed it is.
India’s airport expansion offers an opportunity: Noida International and Navi Mumbai International represent new competitive capacity. Transparent slot allocation and effective use-it-or-lose-it rules could let future airlines build meaningful schedules without penalising those that built the market. The objective should not be to take capacity away from successful airlines. It should be to ensure that infrastructure scarcity does not make serious airline entry almost impossible.
India has consequently travelled from a market where several airlines held shares in the teens to one where a single carrier holds close to two-thirds
Discussion on relaxing India’s rules that bar airport operators from owning airlines could open the door for groups such as Adani or GMR. Adani Airport Holdings sought changes relating to restrictions at Mumbai airport, though it later stated in a filing that it had no plans to enter the airline business. Whether either wants an airline is secondary to the policy question.
On one side, such companies have the capital, expertise and long-term horizon a serious new airline needs. India arguably does not need another under capitalised carrier hoping to survive a fare war. It needs investors capable of building scale.
On the other sits an obvious conflict of interest. An airport operator controls the gates, stands and terminal space every airline requires, and rivals would inevitably question whether access remained neutral. Any relaxation would demand strong safeguards: transparent airport charges, independent slot allocation, equal access and close competition oversight. India should not solve one concentration problem by creating another.
THE OTHER SIDE OF THE ARGUMENT: INDIA NEEDS BIG AIRLINES
There is an important counterpoint. India cannot become so concerned about domestic concentration that it prevents its airlines from achieving the scale required to compete internationally. For decades, much of India’s international traffic has flowed through foreign hubs such as Dubai, Doha and Singapore. That is beginning to change, with IndiGo expanding abroad and Air India rebuilding as a global network airline.
India needs airlines large enough to compete with the world’s aviation giants abroad, while simultaneously needing enough competition to keep its market healthy at home.
These objectives need not conflict. The answer is not to make IndiGo smaller or stop Air India growing, but to give others a realistic chance of growing alongside them.
This is sometimes framed as a task for the Directorate General of Civil Aviation, but DGCA’s principal responsibility is safety. The Ministry of Civil Aviation shapes policy, the Competition Commission of India examines mergers, and airport operators and governments influence access and costs.
DGCA must ensure that any airline entering or expanding meets safety standards — a non-negotiable. Entry barriers can be lowered without weakening safety.
WHAT INDIA CAN DO NOW
No single policy can create competition overnight, but several measures together could help. Aviation fuel taxation and airport charges are an obvious starting point, since a market where only the largest can absorb structural costs will become more concentrated. Slot policy should recognise that access to commercially useful timings can determine whether a newcomer succeeds or fails.
Future mergers deserve careful scrutiny, because a deal that seems harmless nationally can sharply reduce choice on individual city pairs. India should also encourage different types of airlines rather than expecting every entrant to become another IndiGo. A premium carrier, a regional airline, an ultra-low-cost operator and a conventional low-cost carrier can all create competitive pressure in different ways.
Most importantly, policy should make airline survival possible without artificially protecting poorly run businesses. Keeping an unsustainable airline alive does not create competition; letting a well-run one survive does.
TWO POSSIBLE FUTURES
In the first, IndiGo becomes a major global airline, Air India completes its transformation, Akasa grows into a substantial third competitor and one or two well-capitalised new entrants emerge, with new airports giving them room to build networks. India would achieve something it has rarely managed: large airlines, strong balance sheets and genuine competition.
In the second, IndiGo and Air India absorb most incremental capacity, smaller airlines stay marginal and prime slots grow more concentrated. India would still become one of the world’s largest aviation markets, but one overwhelmingly dependent on two groups.
Starting an airline is difficult almost everywhere. Building one in India adds a particular set of challenges
That distinction should sit at the centre of India’s aviation debate. IndiGo deserves enormous credit. Its success demonstrates that an Indian carrier can build enormous scale without abandoning operational efficiency, and restricting it would make little sense. Air India should likewise be allowed to build the global network India has long lacked. But for a country of India’s size and ambition, two giants are not enough.
Aircraft orders and new terminals do not create a healthy aviation industry. Competition does. Too much competition without sustainable economics destroys airlines. Too little eventually weakens the market around them.
India now has the chance to find the balance. The government must make aviation easier to enter without making it easier to fail. Competition authorities must recognise that even relatively small airlines can exert significant pressure on larger rivals. Airport policy must ensure tomorrow’s infrastructure does not reproduce today’s market structure. DGCA must keep protecting safety. And investors must bring the patience to build airlines over decades, not chase market share for a few years.
India has created one of the world’s most successful low-cost airlines and may be rebuilding a national carrier to compete with the best. The next achievement should be an ecosystem in which another serious challenger can emerge alongside them. Because the strongest aviation market is not one where its largest airline is forced to become smaller.
It is one where its competitors are capable of becoming larger.